
How Much Is Insurance on a McLaren?
McLarens are engineering marvels — lightweight, powerful, and thrilling to drive. But insuring one requires understanding their unique cost profile. Here's everything you need to know about McLaren insurance, from annual premiums to strategies that actually lower your rates.
McLaren Insurance Costs by Model
McLaren's lineup spans from entry-level supercars like the GT to exotic hypercars like the Speedtail. Each model carries different insurance premiums based on repair costs, market value, performance characteristics, and the specialized expertise required to service them. Here's the breakdown of what you'll actually pay annually for insurance across McLaren's range:
| Model | Annual Insurance Cost | Key Factors |
|---|---|---|
| McLaren Artura | $3,500–$7,000/yr | Newest model, hybrid powertrain, lower repair costs |
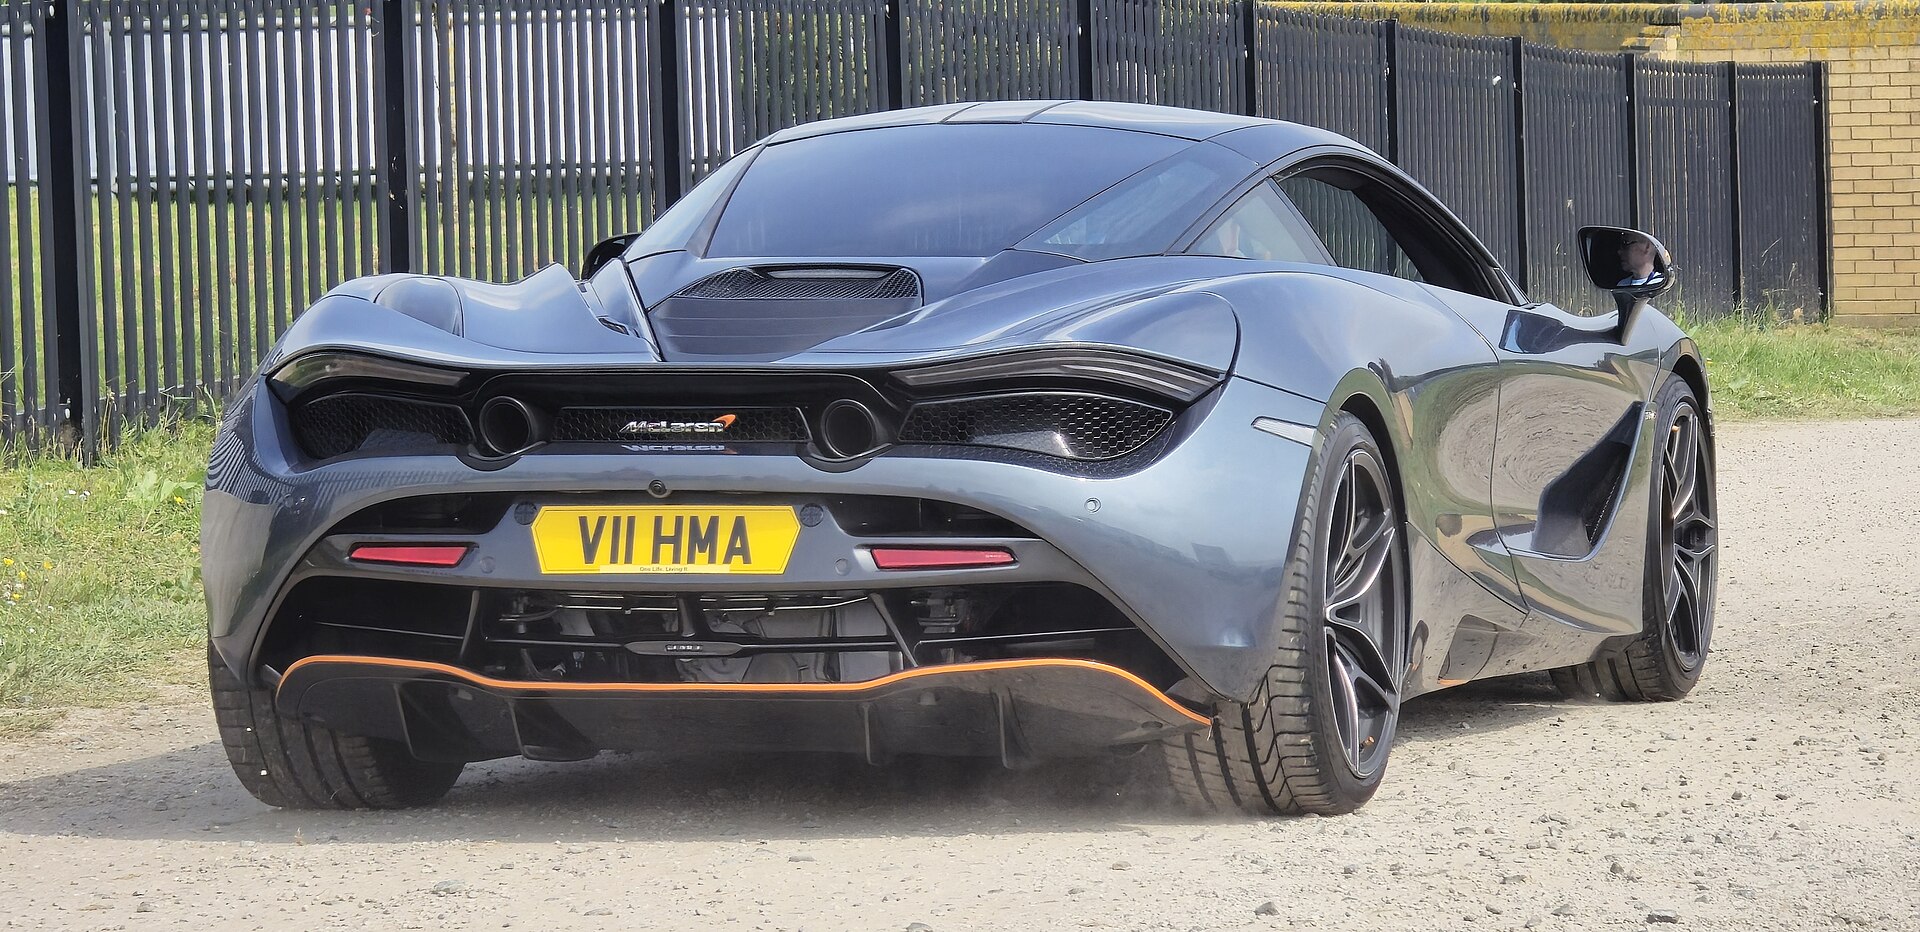
| McLaren 720S/720S Spider | $4,500–$9,000/yr | Mid-range platform, carbon tub, moderate parts supply |
| McLaren 750S | $5,000–$9,500/yr | New generation, hybrid, higher replacement values |
| McLaren 765LT/Spider | $6,000–$11,000/yr | Track-focused, premium materials, specialized repair network |
| McLaren GT | $3,500–$6,500/yr | Grand tourer, lower performance metrics, wider accessibility |
| McLaren 570S/570GT (Used) | $3,000–$6,000/yr | Older platform, depreciated values, established repair base |
| McLaren 600LT (Used) | $4,000–$7,500/yr | Track-oriented, carbon construction, higher claim costs |
| McLaren P1/Senna/Speedtail | $15,000–$40,000/yr | Hypercars, extremely limited supply, specialized insurance required |
These ranges reflect standard comprehensive and collision coverage for drivers aged 30–50 with good driving records and adequate safety features. Younger drivers, those with violations, or anyone in high-risk urban areas will pay significantly more — sometimes 40–60% higher. Conversely, experienced collectors with clean records and stored vehicles can negotiate lower rates through specialty insurers.
The McLaren Insurance Challenge: Carbon Fiber Doesn't Come Cheap
The reason McLaren insurance costs more than you might expect from a "just a sports car" perspective lies in one material: carbon fiber. McLaren pioneered the use of carbon fiber monocoque construction in road cars, which provides extraordinary strength-to-weight ratios. It's the same construction method used in Formula 1, and it's one of the reasons McLarens feel so responsive and efficient.
But from an insurance perspective, carbon fiber is a double-edged sword. Minor accidents that would scratch the paint on an aluminum frame can cause hidden structural damage on a carbon monocoque. A side-impact collision that a conventional supercar might repair for $15,000 can cost $50,000–$100,000+ on a McLaren because the entire section of the carbon tub may need to be replaced rather than repaired.
Limited repair network: McLarens can only be repaired at authorized McLaren service centers or highly specialized independent shops. There are fewer than 200 certified McLaren technicians in North America, compared to thousands of Ferrari and Lamborghini specialists. This scarcity drives labor costs up. A single day of diagnostic work at a McLaren dealer runs $250–$400/hour, compared to $150–$200 at many independent exotic shops.
Specialized training required: McLaren's hybrid powertrains, dual-clutch transmissions, and complex carbon fiber repair procedures require specific training and equipment. Technicians need McLaren certification, which means fewer shops can handle the work, which means less price competition, which means higher repair costs for everyone insuring the car.
Parts supply chain: While McLaren has improved parts availability compared to Ferrari, obtaining certain components still takes weeks or months. If a 765LT needs a carbon fiber body panel, that part may need to be ordered from the UK factory. During the repair period, your car sits in a shop, and you face weeks without transportation. Insurance companies factor this downtime risk into premiums.
Total loss threshold reality: Because repair costs are so high, McLarens reach total-loss status faster than comparable vehicles. An accident that damages the carbon monocoque on a 720S might instantly push that $180,000 car into total-loss territory if repair estimates exceed 70–75% of its actual cash value. Insurance companies know this and price it accordingly.

McLaren vs Ferrari vs Lamborghini Insurance Comparison
When shopping for supercars in the $150K–$300K range, the insurance cost difference between McLaren, Ferrari, and Lamborghini is significant. Here's how they stack up:
| Brand/Model | Typical Annual Insurance | Repair Network Size | Average Claim Payout |
|---|---|---|---|
| McLaren 720S | $4,500–$9,000 | ~150 locations | $35,000–$65,000 |
| Ferrari 488 | $5,500–$10,500 | ~180 locations | $40,000–$75,000 |
| Lamborghini Huracan | $4,000–$8,500 | ~200 locations | $30,000–$60,000 |
| Porsche 911 Turbo S | $3,500–$7,000 | ~500 locations | $15,000–$35,000 |
The Porsche 911 Turbo S is cheaper to insure because it uses conventional aluminum construction and can be serviced at thousands of Porsche dealers worldwide. Lamborghini edges out McLaren slightly because the Volkswagen Group provides better parts availability and more widespread technician access. Ferrari lands at the higher end due to extreme brand prestige and even more limited service centers than McLaren.
Why McLaren's Carbon Construction Matters for Insurance
Understanding carbon fiber is essential to understanding why McLaren insurance costs what it does. Unlike traditional aluminum or steel frames that can be bent back into shape, carbon fiber repairs require one of two approaches: patch repairs (for minor damage) or full section replacement (for structural damage).
For a patch repair on a carbon fiber section, technicians use specialized epoxy resins and lay-up techniques that require a controlled curing environment. This process takes days to weeks, and the repaired area may never have the exact same strength-to-weight ratio as the original. Insurance adjusters therefore default to replacement when dealing with structural damage.
Full section replacement on a carbon monocoque is where costs explode. If the impact damage extends into the central strength members of the tub, the insurance company may determine the vehicle is a total loss — meaning it's cheaper to pay out the car's actual cash value than to repair it. This happens at lower damage percentages on McLarens than on conventional sports cars.
Total loss thresholds: On a typical sports car, insurance companies will total the vehicle if repair costs exceed 70–80% of its current market value. On a McLaren with carbon tub damage, that threshold often drops to 60–70% because of the uncertainty around carbon repair quality and the long-term liability implications. An insurer would rather pay out a $200,000 McLaren than take on the risk of a poorly repaired $200,000 vehicle that might fail catastrophically at speed.
Repair vs. replace decisions: This is where owning a McLaren gets psychologically complicated. You might get in a fender-bender that would be a $5,000 repair on a Mercedes, a $15,000 repair on a Ferrari, and a $35,000 repair on a McLaren — but because the total-loss threshold is lower, the insurance company declares it a total loss and writes you a check instead. You lose the car you love, even though it could theoretically be fixed. This "catastrophic repair cost" risk premium is baked into every McLaren insurance quote.

Best Insurance Strategies for McLaren Owners
There are proven tactics to reduce your McLaren insurance costs while maintaining proper coverage. These strategies work because they address the specific risk factors that insurers use to calculate premiums.
Use Agreed Value Coverage, Not Actual Cash Value
This is the single most important decision you'll make on your McLaren insurance policy. Actual cash value (ACV) coverage reimburses you for your car's depreciated market value at the time of loss. Agreed value coverage locks in a specific agreed amount at policy inception.
For a McLaren, agreed value is almost always better. Because McLarens depreciate slowly and hold value better than most supercars, you want to lock in today's value rather than have an adjuster determine its value months later after the market may have shifted. If you buy a 720S for $180,000 and take agreed value coverage at that amount, you're guaranteed that amount if the car is totaled — regardless of what the market says it's worth two years later.
Choose Your Carrier Carefully
Not all insurance companies understand exotic cars equally. Mass-market carriers like State Farm or Geico will give you online quotes that seem low, but they may deny claims, refuse to use specialty repair shops, or force you into conventional repairs that compromise the car's integrity.
Specialty carriers that focus on exotic vehicles include:
- Hagerty: Best for stored vehicles and collectors. If your McLaren is a weekend-only car, Hagerty's collector coverage can cost 60–70% less than standard policies. Limited annual mileage (1,000–7,500 miles) is required.
- Specialty Underwriters: Companies like American Collectors Insurance and Chubb specialize in exotic vehicles and understand carbon fiber repair issues intimately. They cost more upfront but rarely deny legitimate claims.
- Local Exotic Specialists: Regional insurance brokers who focus on Ferraris, McLarens, and Lamborghinis often have the best rates and most lenient claim handling. They understand that a totaled McLaren from a minor accident is economically irrational, and they're more flexible on repair approaches.
Practice Mileage Management
Insurance premiums directly correlate with annual mileage. A McLaren driven 15,000 miles annually will cost significantly more to insure than one driven 3,000 miles annually. If you don't plan to drive your car extensively, be honest about it on your application. Mileage caps of 5,000–7,500 miles/year can reduce your premium by 20–35%.
The key is accuracy: if you claim 5,000 miles/year but actually drive 12,000, you've committed insurance fraud. Don't do this. It's not worth the risk, and the premium difference isn't that large relative to the car's total cost of ownership.
Install Advanced Security Features
McLarens come with good factory security, but adding aftermarket features can reduce your premium 5–10%. GPS trackers, immobilizers, and steering wheel locks all reduce theft risk, which is significant on high-value exotics.
Bundle With Homeowners or Other Policies
Multi-policy discounts exist even for exotic vehicles. If you bundle your McLaren insurance with homeowners, umbrella, or other policies, you may get 5–15% off your auto premium.
Maintain a Clean Driving Record
This seems obvious, but it's critical. A single at-fault accident or moving violation can increase your McLaren insurance by 25–50%. The cost of defensive driving and patience is tiny compared to the insurance impact of accidents.
McLaren Track Day Insurance: What Happens When You Track Your Car
Many McLaren owners buy the car specifically for track days — weekend circuit events where you can legally drive at speed in a controlled environment. Standard insurance does not cover track day incidents. You need specialized track day coverage.
Track day insurance options: Most tracks and driving events require proof of insurance before you can participate. You have three main options:
- Track-specific policies: Companies like Track Addiction and Rennlist-affiliated insurers offer single-event or annual track day coverage. A single day typically costs $150–$300 depending on the car's value. Annual unlimited coverage for a $250,000 McLaren might cost $2,000–$4,000.
- Endorsements to your standard policy: Some exotic specialists will add track day coverage to your regular policy for an additional premium. This is less common and usually reserved for experienced drivers with excellent records.
- Self-insurance: The most common approach: high-net-worth individuals simply drop their regular insurance for the few hours they're on track and accept the risk. This requires significant capital reserves to handle a potential total loss.
What happens if you crash on track: If you crash your insured McLaren on track and that crash wasn't covered, your standard insurance will deny the claim. The car is totaled, and you're out the full value. This is the biggest financial risk track day drivers face. Don't skip the coverage.
How Auto Monitor Protects McLaren Buyers: Beyond Insurance
While Automonitor doesn't provide insurance, we help McLaren buyers avoid catastrophic financial mistakes that end up costing more than the car itself. Our protection services include pre-purchase inspections (PPI) that specifically assess carbon fiber integrity, and accident history detection that reveals if a car has been previously damaged.
Carbon fiber integrity inspection: During a PPI, we examine the carbon monocoque for signs of previous impact damage or poor repairs. We look for slight weight variations, small cracks, misaligned body panels, and evidence of curing compound residue. A poorly repaired carbon tub might look fine cosmetically but could fail under stress, creating a major liability for you and your insurer. Catching this during PPI saves catastrophic problems later.
Accident history detection: Insurance companies price your premium based partly on the car's accident history. A McLaren that was in an accident three years ago, even if properly repaired, will cost you more to insure for the rest of your ownership. Our detailed history reports reveal whether a car has been in previous claims, which allows you to negotiate the price down accordingly or walk away if the damage was severe.
When you buy through Automonitor's buying service, we connect you with certified inspection partners who understand McLaren-specific issues. We also provide market-rate valuations so you know exactly what a McLaren actually costs in today's market, helping you make informed insurance and financing decisions.
McLaren Model Comparison: Insurance Cost Impact by Variant
Not all McLarens are created equal when it comes to insurance. Here's how specific models and generations stack up:
| Model | Year Range | Est. Annual Insurance | Repair Complexity | Best For |
|---|---|---|---|---|
| 570S | 2015–2019 | $3,500–$5,500 | Medium | Budget-conscious buyers |
| 570GT | 2016–2019 | $3,000–$5,000 | Medium | Grand touring focus |
| 600LT | 2018–2020 | $4,500–$7,500 | High | Track-oriented drivers |
| GT | 2019–Present | $3,500–$6,500 | Medium | Everyday usability |
| 720S | 2017–2023 | $4,500–$8,500 | High | Performance seekers |
| 765LT | 2020–Present | $6,000–$10,500 | Very High | Track-minded collectors |
| Artura | 2021–Present | $3,500–$7,000 | Very High | Newest technology adopters |
| 750S | 2023–Present | $5,000–$9,500 | Very High | Modern platform preference |
The 570S and GT offer the most affordable insurance because they're older platforms with established repair techniques. The 765LT and Artura are most expensive due to cutting-edge construction and limited technician familiarity. The sweet spot for value is usually a 2019–2021 720S — old enough for insurance to have stabilized, new enough to be reliable and desirable.
Find Your Perfect McLaren at the Right Price
Automonitor connects you with verified McLaren listings, provides certified inspections, and helps you understand the true cost of ownership before you buy.
Browse McLarens →What Increases Your McLaren Insurance Premium: The Full List
Insurance companies use sophisticated algorithms to calculate risk. For McLaren owners, here are the factors that most significantly impact your rates:
- Age and experience: Drivers under 25 or over 75 pay 30–60% higher rates. The algorithm assumes less experienced judgment.
- Driving record: A single at-fault accident increases your premium 25–40%. Multiple violations or accidents can double your rate.
- Location: Urban areas with high accident and theft rates cost 20–40% more than rural areas. Parking a McLaren in downtown Los Angeles will cost significantly more than keeping it in rural Colorado.
- Annual mileage: Every 5,000 miles of additional annual driving adds roughly 10–15% to your premium. This is why low-mileage coverage options exist.
- Vehicle modifications: Engine tuning, lowered suspension, or aftermarket parts can add 15–30% to your premium because they increase accident severity risk.
- Prior claims history: If this McLaren has been in previous accidents or insurance claims, your premium increases 20–50%, even if the damage was minor and properly repaired.
- Credit score: Insurance companies correlate credit score with claim risk. A poor credit score can add 10–25% to your rate regardless of driving record.
- Marital status and household composition: Married drivers pay less than single drivers. Additional household drivers increase risk.
How to Actually Lower Your McLaren Insurance Costs
Beyond the strategies mentioned earlier, here are additional tactics that work:
Increase your deductible: Jumping from a $500 deductible to a $2,500 deductible can reduce your premium by 20–30%. This works if you have sufficient emergency funds to cover that deductible without financial stress. Most McLaren owners do, so this is a reasonable trade-off.
Ask about loyalty discounts: If you've insured your car with the same company for 3+ years with no claims, you may qualify for loyalty discounts of 5–15%. Most people don't ask, so they never get it.
Switch carriers every 3 years: Insurance companies offer best rates to new customers. After 3 years, that rate tends to creep up. Getting competing quotes every few years often reveals that switching saves $500–$1,500 annually.
Take a defensive driving course: Courses specifically for sports car owners (not standard driver's ed) can qualify you for 5–10% discounts on comprehensive and collision coverage. The course costs $200–$500, so you break even after one year of savings.
Use your car for the activity it's designed for: This sounds backwards, but cars used as intended (driven regularly, maintained properly, used for their purpose) often have better insurance claims outcomes. A McLaren that sits in a garage for years develops hidden problems (seal leaks, battery degradation, tire flat-spotting) that cost more to fix than normal wear from actual driving. Some insurers price this into discounts for actively-driven vehicles.
The Real Cost of Insuring a McLaren: Final Thoughts
A McLaren is one of the most efficient, best-engineered supercars ever produced. But efficiency and engineering complexity create unique insurance challenges. The carbon fiber construction that makes the car light and fast creates repair costs that would astound owners of conventional vehicles. The specialized technician network that keeps McLarens running properly creates scarcity that drives insurance rates up.
On a $200,000 McLaren, you're looking at $5,000–$10,000 annually for comprehensive insurance coverage. That's 2.5–5% of the vehicle's value per year, compared to 1–2% for most conventional luxury cars. Over a three-year ownership cycle, insurance might cost you $15,000–$30,000 on top of fuel, maintenance, and depreciation.
This is not a reason to avoid buying a McLaren. It's simply a reason to understand the full cost of ownership before you commit. The driving experience is extraordinary, the cars are genuinely reliable by supercar standards, and the way they hold value makes long-term ownership economical. But eyes open: factor insurance into your budget, choose your coverage strategy carefully, and work with carriers who understand exotic vehicles.
When you're ready to buy, Automonitor helps you find the right McLaren at the right price, arrange certified inspections that reveal hidden issues, and understand the true cost of ownership. We'll make sure you're not surprised by insurance premiums, repair costs, or depreciation when you take delivery.
Get Expert Help Finding Your McLaren
Our concierge buying service handles everything: sourcing, inspections, insurance consultations, and negotiations so you buy with confidence.
Start Your Search →