
Can You Finance a Rolls-Royce? Complete Financing Guide for 2026
Owning a Rolls-Royce is the ultimate luxury fantasy. But the real question isn't whether you can afford to buy one — it's whether you can afford to finance one, and more importantly, whether the financing options available actually make sense for your wealth level. Here's the complete breakdown of every financing pathway to Rolls-Royce ownership.
The Short Answer: Yes, But It's More Complex Than You Think
You can absolutely finance a Rolls-Royce. Multiple institutional lenders offer specialized financing for ultra-luxury vehicles, including dedicated Rolls-Royce Financial Services (which operates through BMW's financial division), regional exotic car lenders, and private wealth financing structures. But unlike financing a Ferrari or Lamborghini, Rolls-Royce ownership financing sits at the intersection of asset financing and bespoke wealth management — it's less about monthly payments and more about whether you're financially positioned to own a depreciating asset worth $330,000 to $460,000+.
The real answer to "can you finance a Rolls-Royce?" isn't "yes or no" — it's understanding whether financing is actually the right move for your financial situation, what rates and terms you can expect, which lender options exist, and how the total cost of ownership factors into your decision. This guide covers all of it.
Financing Options for Rolls-Royce: Who Actually Lends on Ultra-Luxury Cars
Unlike mass-market vehicles, Rolls-Royce financing doesn't come from your local bank or credit union. The universe of lenders is much smaller and more specialized. Here are your actual options:
Rolls-Royce Financial Services (Through BMW Financial)
This is the official financing channel, and it's the most accessible for qualified buyers. Rolls-Royce Motor Cars partners with BMW Financial Services for all institutional lending. When you finance through an authorized Rolls-Royce dealer, you're actually getting BMW Financial's underwriting and terms, just packaged for luxury buyers. These loans typically offer:
- APR Range: 5.9% to 10.2% depending on credit score, loan-to-value ratio, and vehicle type
- Down Payment: Typically 20–30% required; some programs accept 15% for exceptional credit (750+)
- Loan Terms: 48–72 months standard; 84–96 months available for specific models
- Application Process: Can be completed through a Rolls-Royce dealer; approval typically takes 3–7 business days
- Advantage: Factory-backed, reliable, straightforward, often includes gap insurance
BMW Financial Services is surprisingly accessible because BMW targets middle-wealth buyers (by ultra-luxury standards) and understands that many Ghost and Cullinan buyers are on their first super-luxury purchase. They're more willing to finance lower credit scores and weaker debt-to-income ratios than you might expect.
Specialty Exotic Car Lenders
Companies like JJ Best Banc and Woodside Credit Union specialize in exotic car financing, including Rolls-Royce. These lenders often compete directly with manufacturer financing by offering comparable or better terms to their most qualified borrowers:
- APR Range: 4.9% to 8.5% for borrowers with excellent credit (760+) and strong financial profiles
- Down Payment: 15–25% depending on lender and vehicle condition
- Loan Terms: 48–84 months; some offer up to 96 months for used models
- Underwriting: Often more flexible on debt-to-income ratios; may focus more on total net worth than traditional metrics
- Advantage: Competitive rates, experienced with exotic vehicles, flexible structures
JJ Best and Woodside are legitimate options if you have stellar credit and a substantial down payment. Their rates can beat BMW Financial by 1–2%, which on a $300,000 loan results in $3,000–$6,000 annual savings.
Rolls-Royce Motor Cars Direct Dealer Financing
Not all dealers work through institutional lenders. Some high-end dealers (particularly in major markets like Los Angeles, Miami, and New York) have in-house financing or partnerships with wealth management firms. These options vary dramatically by location and dealer.
- APR Range: Highly variable; can be 4.5%–12% depending on the dealer's funding sources
- Down Payment: 25–40% often required
- Terms: More flexible; some dealers structure deals as asset-backed lending rather than traditional auto loans
- Risk Factor: Less regulatory oversight; make sure any agreement includes standard auto loan protections
Dealer financing can be attractive if the dealer has a strong relationship with a private lender or credit union, but you need to shop rates carefully. Some dealers mark up interest rates substantially.
Rolls-Royce Leasing Programs
This deserves its own section because leasing a Rolls-Royce is actually the most popular financing method for first-time ultra-luxury buyers. A 3-year lease on a new Ghost costs roughly $4,500–$5,800 per month, with all maintenance, insurance, and repairs covered by the manufacturer. For many buyers, this eliminates the depreciation risk and major repair costs that make ownership financially stressful.
Lease vs. Finance Comparison: A Ghost financed at 7% APR on $330,000 with 25% down ($82,500) costs $4,200/month for 60 months, plus insurance ($500–$800/month), maintenance ($800–$1,200/month), and fuel ($300–$500/month). Total: roughly $5,800–$6,700 per month. A lease? $4,500–$5,500/month all-in, with no depreciation risk and no repair surprises. For buyers without certainty about long-term ownership, leasing is the smarter financial move.
Rolls-Royce Models and Monthly Financing Payments: What You'll Actually Pay
Here's the reality of monthly payments on each current Rolls-Royce model, based on realistic financing scenarios (25–30% down, 60–72 month terms, 6–8% APR):
| Model | MSRP | Typical Financed Amount | Monthly Payment (60 mo, 7%) | Total Interest Paid |
|---|---|---|---|---|
| Ghost | $330,000–$380,000 | $245,000–$280,000 | $4,500–$5,200 | $25,000–$32,000 |
| Spectre (New) | $420,000–$480,000 | $310,000–$355,000 | $5,700–$6,500 | $31,000–$39,000 |
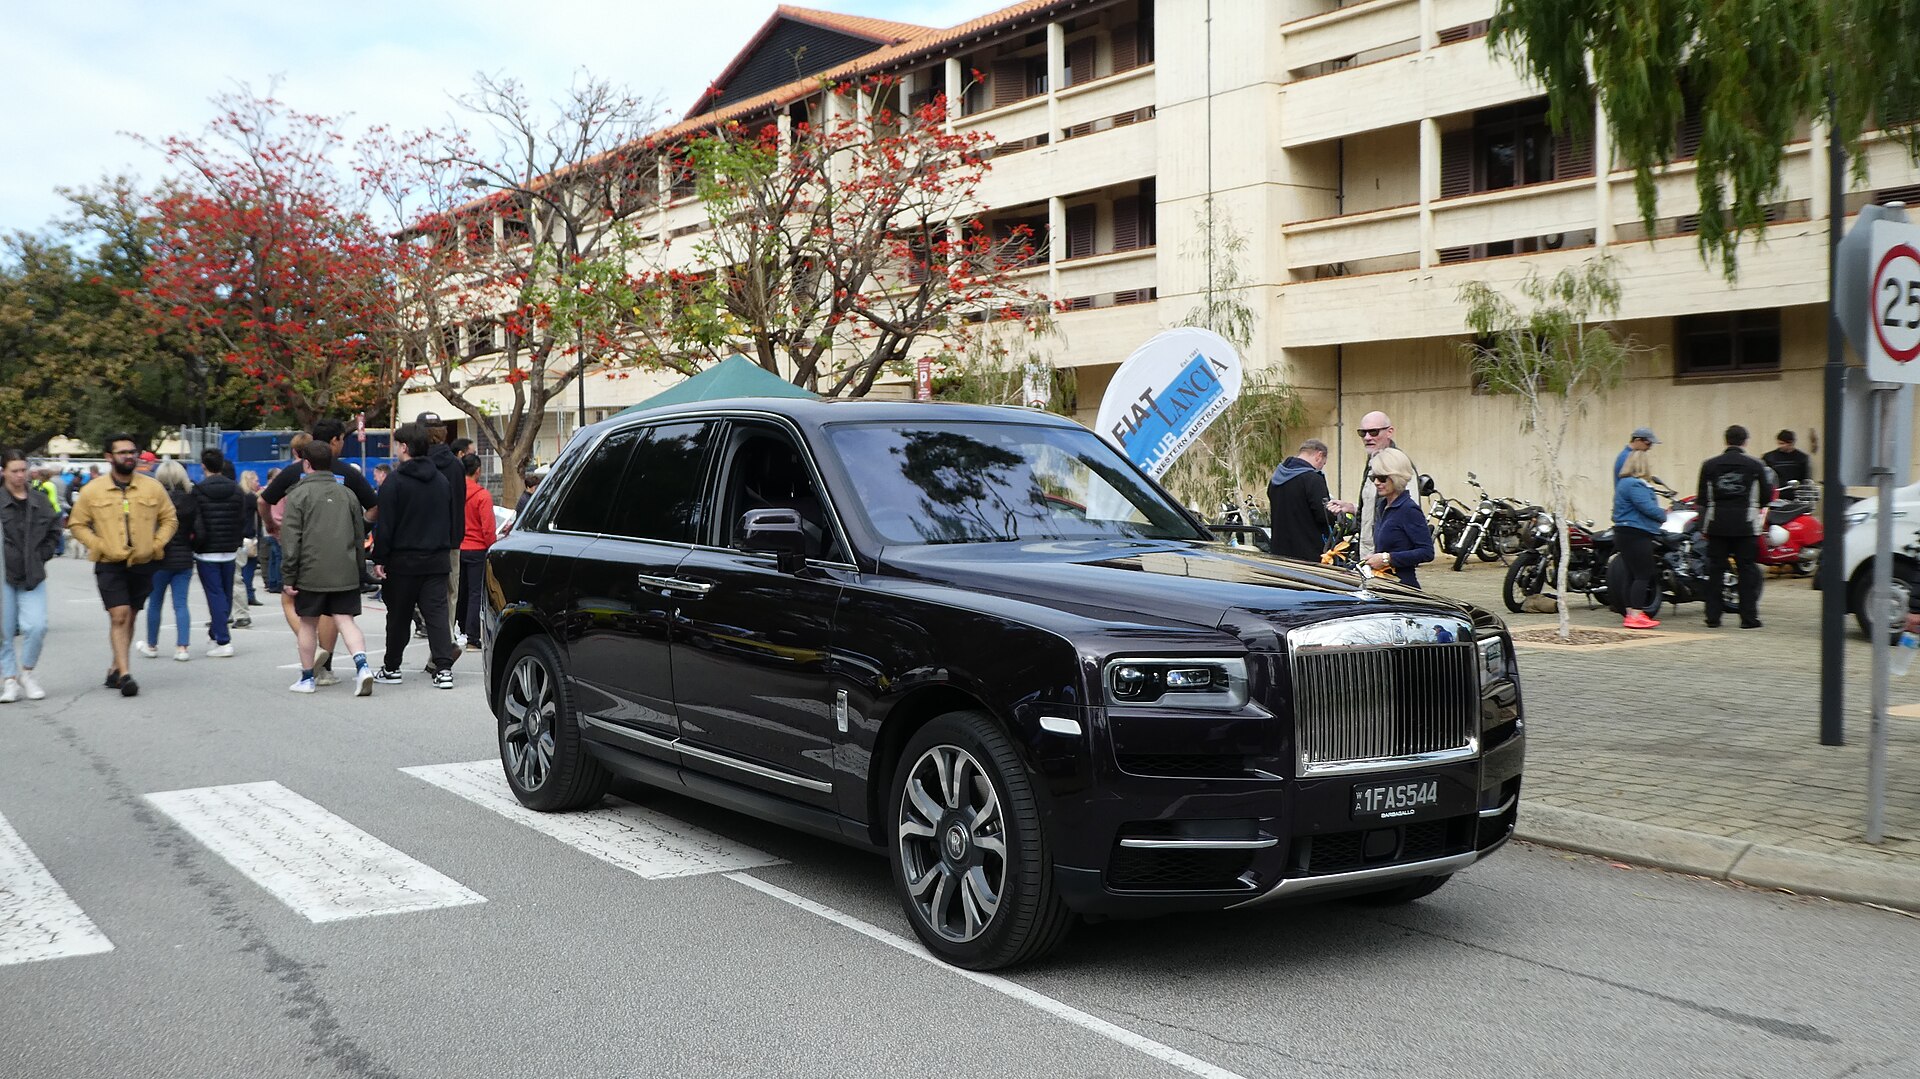
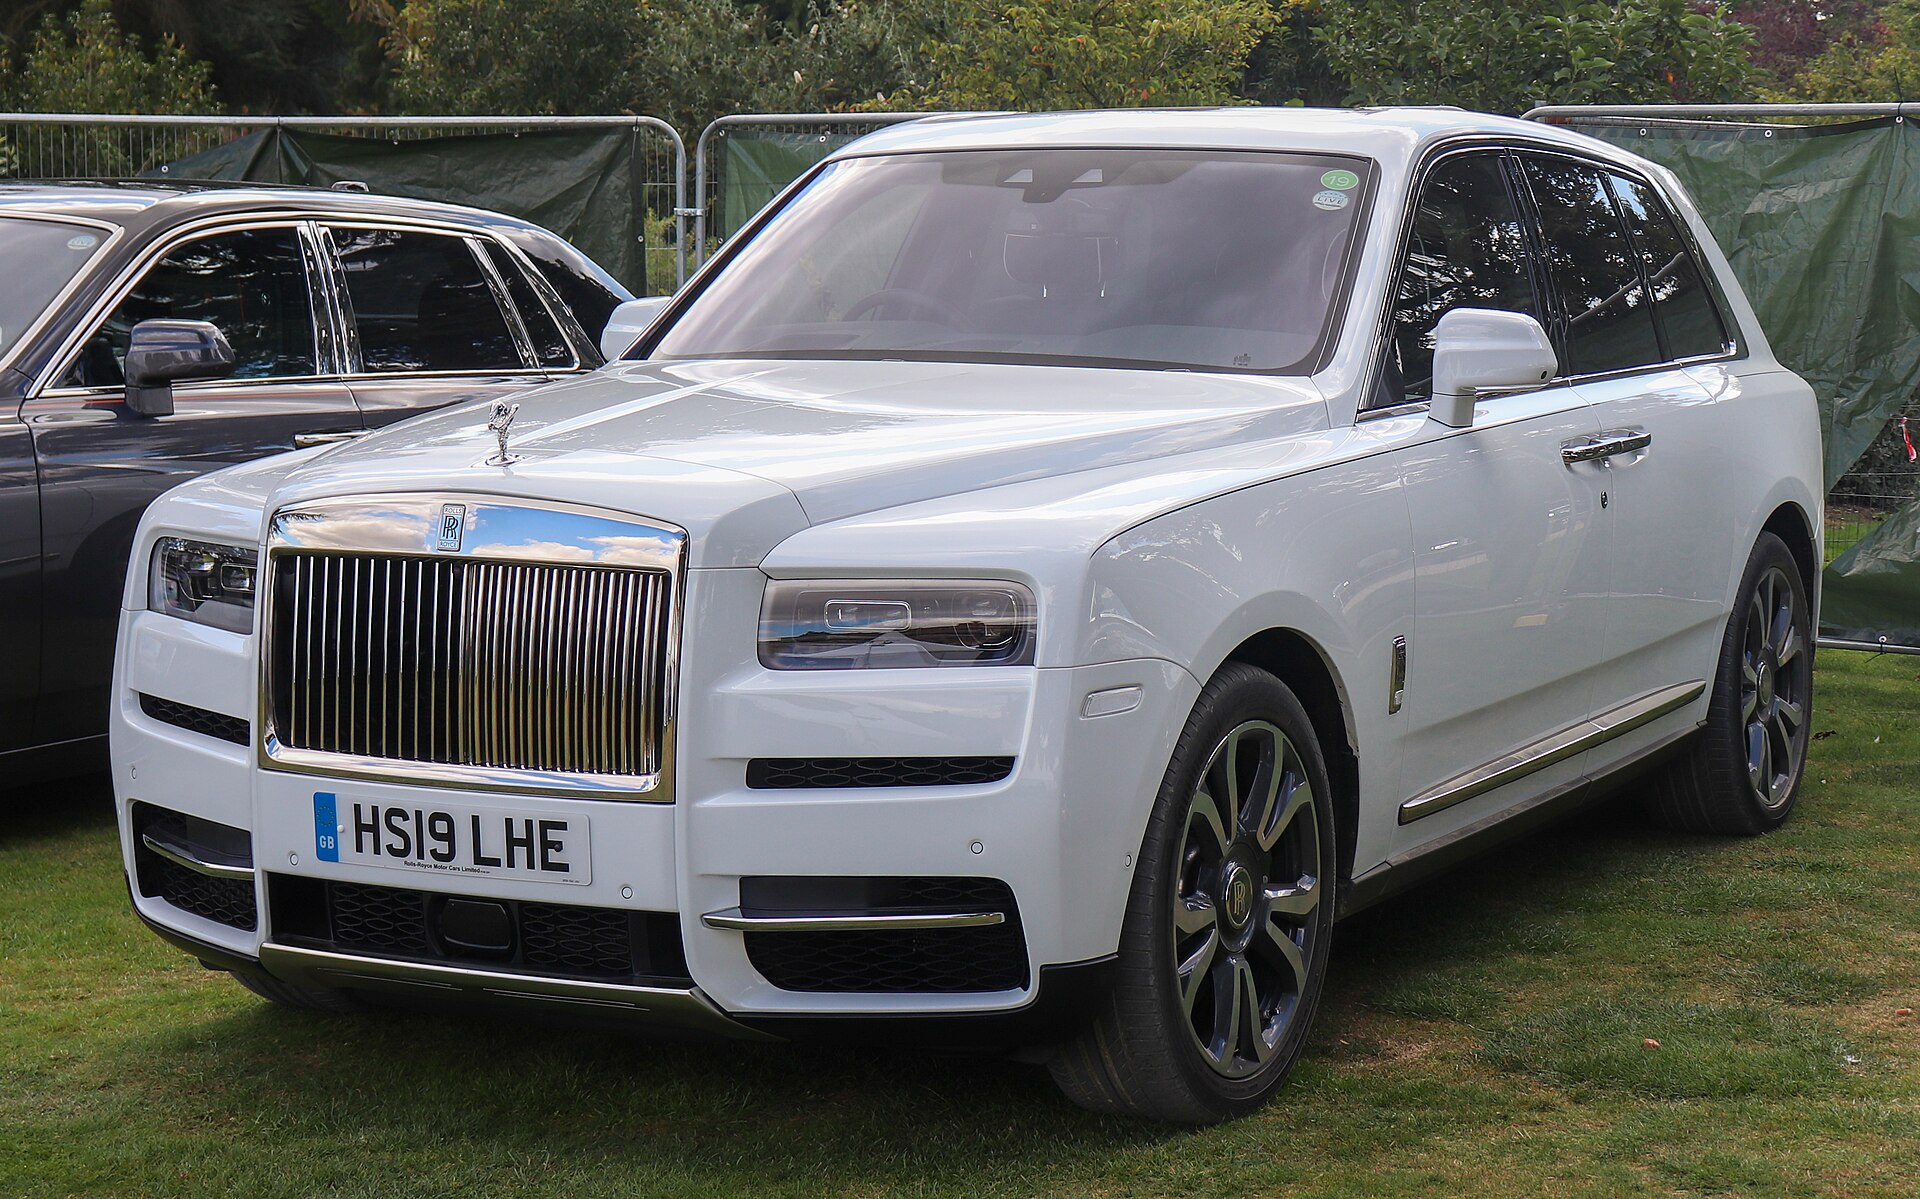
| Cullinan (SUV) | $370,000–$420,000 | $275,000–$310,000 | $5,000–$5,700 | $27,000–$34,000 |
| Phantom | $460,000–$530,000 | $340,000–$390,000 | $6,300–$7,200 | $36,000–$43,000 |
These numbers assume 25–30% down and 6–7% APR (realistic for excellent credit). With higher interest rates (8–9%) or lower down payments (15%), add 15–25% to the monthly payment.
Now, here's the critical context: a $5,000/month payment on a Rolls-Royce Ghost is not the same as a $5,000/month payment on a BMW 7 Series. The Ghost payment is the baseline — insurance, maintenance, fuel, and eventual depreciation are additional. Total cost of ownership typically runs $7,000–$9,000 per month, every month, for the life of the loan.
The Bespoke Option Cost: How Custom Specifications Drive Up Price and Financing Amount
Standard Rolls-Royce models start at the prices listed above, but the brand's selling point is complete customization. Bespoke options — custom paint, hand-stitched leather, personalized audio systems, unique interior materials — commonly add $80,000 to $150,000+ to the final price. Some truly exceptional commissions have exceeded $200,000 in bespoke upgrades.
This matters for financing because the financed amount changes. A Ghost with standard options might finance at $245,000. A Ghost fully configured with premium bespoke upgrades could finance at $380,000+. That $135,000 difference means $2,100 more in monthly payments, or $75,600 in additional interest over 60 months.
Financing Strategy: If you're financing a Rolls-Royce, resist the urge to max out bespoke options. Every $10,000 in additional customization costs you approximately $155 per month in financing costs (over 60 months at 7% APR). Choose 3–4 meaningful customizations rather than every available upgrade.
Credit and Financial Requirements for Rolls-Royce Financing
Unlike financing a Lamborghini or Ferrari, Rolls-Royce financing is surprisingly accessible from a credit perspective, but requires substantial net worth documentation.
Minimum Credit Score
BMW Financial Services and specialty lenders will typically consider applications with a credit score of 680+, though approval is not guaranteed. However, meaningful rate discounts require scores above 740:
- 680–719: Approve-able but expect APR of 8–10%
- 720–759: Typical APR range of 7–8.5%
- 760+: Competitive APR of 5.9–7.5%; access to promotional rates from specialty lenders
Credit score matters less than you'd think because Rolls-Royce buyers have alternative proof of creditworthiness — substantial down payments, investment portfolios, business ownership, or real estate equity. A buyer with a 680 credit score and $200,000 cash down might get approved faster than someone with a 750 score and no down payment.
Down Payment Requirements
All Rolls-Royce financing requires a meaningful down payment. The question is how much:
- BMW Financial: 20–30% standard; 15% for exceptional credit with strong income/net worth documentation
- JJ Best/Specialty Lenders: 15–25% typical; lower percentages available for borrowers with $2M+ net worth
- Dealer Financing: 25–40% often required, depending on dealer relationships and lender
For a $330,000 Ghost, a 25% down payment means $82,500 cash due at signing. For a $460,000 Phantom, that's $115,000. These aren't token deposits — they're serious capital requirements that weed out impulse buyers.
Debt-to-Income Ratio
This is where Rolls-Royce financing diverges from standard auto lending. Traditional lenders cap debt-to-income (DTI) at 43–50%. Rolls-Royce lenders are more flexible, particularly BMW Financial, which recognizes that ultra-wealthy buyers often have lower traditional employment income but substantial net worth.
Real-world example: A business owner with $8 million in liquid net worth but only $300,000 in annual W2 income might have a DTI of 180%+ based on traditional calculations. BMW Financial would likely approve them because they focus on absolute ability to pay and collateral value, not ratios. Meanwhile, a salaried employee with a 45% DTI and a 750 credit score might struggle to get approval.
Net Worth Verification: Expect lenders to request documentation of net worth — investment statements, property valuations, business valuations, or bank statements showing liquid reserves. The requirement varies by lender and down payment amount, but if you're putting down less than 20%, net worth verification is standard.
Leasing vs. Buying a Rolls-Royce: The Financial Decision Tree
This is the most important financial decision in Rolls-Royce ownership. Many ultra-wealthy buyers choose leasing specifically to avoid the complexity and cost of ownership. Here's how to decide:
Lease a Rolls-Royce If:
- You want to drive a new model every 3 years
- You're uncertain about long-term ownership or commitment
- You want guaranteed maintenance and no surprise repair costs
- You're averse to depreciation risk (some Ghosts lose 40–50% in first 3 years)
- Your primary motivation is status/prestige rather than long-term asset ownership
Lease costs: $4,500–$5,500/month all-in for Ghost; $5,700–$6,500/month for Spectre; $5,000–$6,000/month for Cullinan; $6,000–$7,000/month for Phantom.
Finance/Buy a Rolls-Royce If:
- You intend to keep the car 5+ years and want unlimited mileage
- You're committed to the prestige and brand ownership (not just renting the status)
- You can tolerate depreciation as a cost of ownership
- You want flexibility to customize extensively (leases have limited personalization)
- You have specific use cases (collection vehicle, business use, international travel)
Ownership costs: $5,800–$7,200/month for Ghost (financing) plus insurance, maintenance, fuel, and eventual depreciation loss of $4,000–$8,000/month amortized over ownership period.
For most first-time Rolls-Royce buyers, leasing is the smarter financial decision. The monthly payment is lower, all costs are predictable, and you avoid catastrophic depreciation. Ownership makes sense when you're committed to keeping the car 5+ years or have it as part of a larger collection.
Used Rolls-Royce Financing: Lower Prices, Higher Rates, Better Values
The used Rolls-Royce market is less liquid than new models, but financing options exist and often provide better value. Used Rolls-Royce pricing typically breaks down as:
| Age / Mileage | Typical Price | Expected Financing APR | Monthly Payment (25% down, 60 mo) |
|---|---|---|---|
| 1–2 Years Old, Under 5K Miles | $275,000–$320,000 | 6.5–8% | $3,800–$4,400 |
| 3–4 Years Old, 10K–20K Miles | $220,000–$280,000 | 7–8.5% | $3,200–$4,000 |
| 5–7 Years Old, 30K–50K Miles | $180,000–$240,000 | 7.5–9% | $2,700–$3,600 |
| 8–10 Years Old, 60K+ Miles | $140,000–$200,000 | 8–10% | $2,100–$3,000 |
Used Rolls-Royce financing typically carries higher APRs (0.5–1.5% higher) than new car financing because older vehicles have more uncertainty and depreciation risk. However, the absolute monthly payment can be 30–40% lower because the financed amount is significantly smaller.
Strategy for used cars: A 4-year-old Ghost with 15,000 miles might cost $250,000 versus $330,000 for a new one. Financing $187,500 (with 25% down) at 8% for 60 months is $3,750/month versus $4,500+ for the new car. The used option saves $750/month while providing access to models with proven reliability (no unknowns).
Rolls-Royce Financing: Lender Comparison and Application Process
Here's how the main lending options stack up:
| Lender | APR Range | Down Payment | Min Credit Score | Application Time | Best For |
|---|---|---|---|---|---|
| BMW Financial (Official) | 5.9–10.2% | 15–30% | 680 | 3–7 days | Straightforward buying from dealer |
| JJ Best Banc | 4.9–8.5% | 15–25% | 720 | 5–10 days | Borrowers with excellent credit |
| Woodside Credit Union | 5.5–9% | 15–25% | 700 | 7–14 days | Member financing; requires membership |
| Local Dealer Financing | 6–12% | 25–40% | 680 | 1–3 days | Quick deals with large down payments |
| Rolls-Royce Lease | N/A | $2,500–$5,000 acquisition | 700 | 7–14 days | Short-term ownership, low commitment |
The Rolls-Royce Financing Application Process: What to Expect
Here's the step-by-step process for securing Rolls-Royce financing:
Step 1: Pre-Approval (1–2 Days)
Contact your chosen lender with basic information: desired purchase price, proposed down payment, approximate credit score, and general net worth overview. You don't need full documentation yet — just enough for the lender to indicate whether approval is likely.
Step 2: Full Application & Documentation (3–5 Days)
Once you've identified a specific vehicle or are ready to move forward, submit a full application. Required documentation typically includes:
- 2 years of tax returns (or 1099s if self-employed)
- Recent pay stubs (if employed)
- Recent bank statements showing down payment funds
- Investment account statements (to verify liquid net worth)
- Recent credit report authorization
- Vehicle identification and details
This is more documentation than a typical auto loan but less than mortgage underwriting. Budget 2–3 hours to compile everything.
Step 3: Underwriting & Appraisal (5–10 Days)
The lender reviews your financials, orders a vehicle appraisal, and verifies employment and assets. For BMW Financial, this is usually straightforward. For specialty lenders, expect more scrutiny if your credit score is below 700 or down payment is below 20%.
Step 4: Approval & Funding (1–3 Days)
Once approved, the lender issues loan documents. You review and sign, and funds are typically available within 1–3 business days. Total timeline from application to funded: 7–14 days for most cases.
Special Financing Considerations for Rolls-Royce Ownership
Insurance Impact on Financing
All lenders require proof of insurance before funding. For a Rolls-Royce, this typically means insuring the car at an agreed value of 90–95% of the purchase price. Insurance costs run $1,500–$3,000 per year depending on age, usage, and driving record — far higher than mass-market vehicles. Some lenders may require proof that you've secured insurance before approving the loan.
Gap Insurance
Gap insurance (which covers the difference between your loan balance and the car's value in a total loss) is standard on new Rolls-Royce financing through BMW Financial. For specialty lenders or used cars, gap insurance is often optional but highly recommended — new Rolls-Royce models can depreciate $40,000–$60,000 in the first year, meaning you could easily owe more than the car is worth in the event of a total loss accident.
Warranty and Service Considerations
New Rolls-Royce models come with a 4-year/50,000-mile warranty, which covers major repairs and maintenance. However, once warranty expires, maintenance costs can be substantial ($3,000–$5,000 annually for routine service, $10,000–$25,000 for major repairs). This should factor into your decision to finance. If you finance for 60 months, you'll likely own the car warranty-free for years 5–7, when unexpected repairs are more likely.
Residual Value and Depreciation
Rolls-Royce depreciation is complex. Some models (particularly limited-edition variants and the new Spectre) are holding value well, with 3-year depreciation around 25–30%. Others (older Ghosts, heavily used Phantoms) depreciate 40–50% in 3 years. This matters for financing because your loan-to-value ratio worsens as the car depreciates. By year 3, you could owe $200,000 on a car worth $160,000.
This is another reason leasing makes financial sense — you avoid the risk of being underwater on your loan.
Red Flags When Financing Rolls-Royce: When NOT to Do It
You're stretching to afford the down payment. If financing the down payment itself, or depleting emergency savings to make it, the car is not affordable. True affordability means you can cover the down payment without touching retirement accounts, emergency funds, or portfolio positions.
Your income doesn't support the monthly payment. The golden rule: your car payment shouldn't exceed 15% of gross monthly income. If your gross income is $15,000/month ($180K annually), your car payment shouldn't exceed $2,250/month. A Rolls-Royce at $5,000+/month requires $33,000+ in gross monthly income ($400K+/year). If your income doesn't support it, financing is too risky.
You're financing the entire car beyond 60 months. 72–84 month loans on Rolls-Royce are available but dangerous. You'll be paying interest for years after the car's novelty fades. Additionally, maintenance costs skyrocket after year 5, and you'll still be making payments while facing $10,000+ annual repair costs. Stick to 48–60 month terms or go with leasing.
You haven't secured insurance quotes yet. Before applying for financing, get actual insurance quotes. Some Rolls-Royce models cost $2,500+/year to insure. Add that to your financing calculation before committing. If the total monthly cost (payment + insurance + fuel + maintenance) exceeds 20% of gross income, it's too expensive.
You're financing from a dealer with no official lender affiliation. If a dealer claims to have financing but can't specify which lender or shows financing documents without clear lender identification, walk away. Predatory lending exists in the luxury market, and unclear financing structures are a massive red flag.
Frequently Asked Questions About Rolls-Royce Financing
Can I finance a Rolls-Royce with a 650 credit score?
Technically yes, but expect higher rates (9–10% APR) and potentially a requirement for a larger down payment (30%+). You'll have better luck with specialty lenders than BMW Financial if your score is below 680. Consider addressing credit issues before applying if possible.
What happens to my financing if I buy a used Rolls-Royce without a warranty?
Your monthly payment is the same, but your financial risk increases substantially. A used Rolls-Royce without a warranty could require $15,000–$25,000 in unexpected repairs. Budget 10–15% of the purchase price annually for potential maintenance as a hedge against this risk.
Can I refinance a Rolls-Royce into a longer loan term if payments are too high?
Yes, but it's costly. Refinancing extends your interest payments significantly. If you financed for 60 months at $5,000/month and refinance into an 84-month term to reduce payments to $3,750/month, you'll pay $90,000 more in interest. Only refinance if your financial situation genuinely changed, not as a payment relief strategy.
Is it better to finance or lease if I'm uncertain about long-term ownership?
Lease, without question. Leasing allows you to exit the commitment in 36 months with predictable costs. Financing locks you into a 5–7 year financial commitment, and selling early results in substantial losses (you'll owe more than the car is worth in most scenarios).
Can I trade in my current car toward a Rolls-Royce down payment?
Yes. Lenders will typically accept trade-in equity as part of your down payment. However, the Rolls-Royce market is niche — dealers and lenders prefer cash down payments. If you're trading in a $50,000 vehicle and need to finance $200,000 to reach your desired down payment, some lenders view this as a red flag. Ideally, at least 50% of your down payment should be cash.
What if I buy a Rolls-Royce outside the US — can I finance it?
Financing options are limited outside the US. Some international lenders serve specific markets (UK, Germany, Middle East), but you'll typically need to finance through a dealer in that country or use private wealth managers. US-based auto financing doesn't typically cross borders.
Related Luxury Financing Guides
Rolls-Royce financing is part of the broader luxury car acquisition ecosystem. If you're exploring Rolls-Royce ownership, these related guides from Automonitor provide important context:
- How to Finance an Exotic Car: Comprehensive Guide for Supercars and Luxury Vehicles
- Can You Finance a Ferrari? Financing Options and Monthly Payments
- Can You Finance a Lamborghini? Complete Financing Guide
- Can You Finance a Bentley? Bentley Financing Options Explained
- How Much Is Insurance on a Rolls-Royce? True Cost of Coverage
- What Are the Hidden Costs of Owning an Exotic Car?
- How Much Does It Cost to Own an Exotic Car Per Year? Full Breakdown
- What Should I Look for When Buying a Used Rolls-Royce?
- How to Negotiate the Price of an Exotic Car: Expert Tactics
- What Is the Process of Buying a Supercar? Complete Buyer's Guide
External Resources for Rolls-Royce Financing
For additional research and current pricing, check these authoritative sources:
- Rolls-Royce Motor Cars Official Site — Current models, specifications, and dealer locator
- JJ Best Banc — Specialty exotic car lender with competitive rates
- Woodside Credit Union — Luxury vehicle financing options
- Hagerty — Exotic car valuations and market data
- Kelley Blue Book — Used car pricing and valuation tools
The Final Verdict: Should You Finance a Rolls-Royce?
Yes, you can finance a Rolls-Royce. The institutional infrastructure exists, multiple lenders compete for your business, and approval is possible for borrowers with good credit and meaningful down payments.
But financing a Rolls-Royce and affording a Rolls-Royce are different questions. The monthly payment is only 25–30% of the true ownership cost. Insurance, maintenance, fuel, and depreciation add another $2,000–$4,000 per month to your commitment. Total ownership costs can reach $7,000–$10,000 monthly for Phantom models.
If your net worth is below $3 million, your annual income is below $400,000, or you're uncertain about long-term ownership, leasing is almost certainly the better financial choice. Rolls-Royce has optimized their lease program specifically for this demographic.
If you have substantial net worth, stable high income, and genuine commitment to ownership, financing becomes a strategic decision — whether to take 5–7 year financing at 6–8% interest, or preserve cash and invest elsewhere while using a leased vehicle as your transportation.
The real question isn't "can you finance a Rolls-Royce?" It's "does financing a Rolls-Royce make financial sense for your situation?" Use this guide to answer that question honestly, and you'll make a decision you won't regret — whether that's to finance, lease, or wait until you're in a stronger financial position.
For help navigating the Rolls-Royce buying process, whether financing or leasing, Automonitor's concierge buying service connects you with verified dealers, secures the best financing terms, and handles the entire transaction. We've helped dozens of buyers find their ideal Rolls-Royce at the best possible price and terms.
Expert Financing Consultation for Rolls-Royce Buyers
Automonitor analyzes your financial situation against current lending rates and helps you determine whether financing, leasing, or purchasing outright makes the most sense for your Rolls-Royce ownership goals.
Get a Financing Assessment →